Week of October 19-23
Corporate earnings and inflation in Europe and Japan keep markets focused.
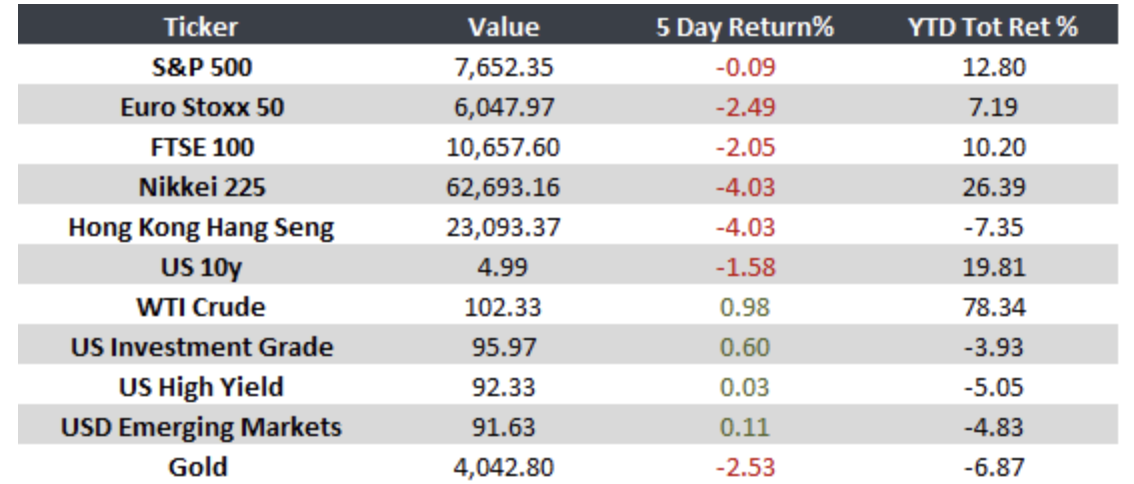
The quarterly earnings season generated volatility, with AI and valuations at the center of the debate. Meanwhile, inflation picked up in Europe and Japan, and Brazil prepares for its presidential runoff.
United States
- With 24% of the S&P 500 reporting, 83% beat earnings estimates and profits are growing 31% year over year. AI spending and valuations weighed on semiconductors. Jobless claims fell to 194,000.
Europe
- Germany’s producer prices rose 6.7% year over year in September, driven by energy. In the U.K., inflation reached 3.5%, its highest since October 2025, and unemployment fell to 4.7%.
Japan
- Annual inflation rose to 2.1% in September, its highest level since December 2025, and the trade deficit widened due to higher oil purchases (+51.1%).
China
- The economy grew 4.5% year over year in Q3 2026, above expectations and supported by tech exports, although domestic demand remains weak. Industrial production rose 5.5% in September.
Argentina
- Economic activity fell 1.7% year over year in August, affected by industry and commerce. In contrast, retail sales grew 24.3% year over year.
Brazil
- Brazil decides its presidency on October 25 in a runoff between Lula and Flávio Bolsonaro, with tight polls. Markets remain focused on the fiscal and economic outlook.
Mexico
- Annual inflation rose to 3.62% in the first half of October, slightly above expectations. Retail sales grew 3.3% year over year in August, driven by e-commerce.
“Know what you own, and know why you own it.”
— Peter Lynch
UPCOMING EVENTS
- In the United States, the FED’s monetary policy decision will be announced on 10/28
- In the United States, the advance estimate of GDP growth for Q3 will be released on 10/29
Monitor: