Week of November 2-6
U.S. elections, inflation in Europe, and rate decisions set the global agenda.
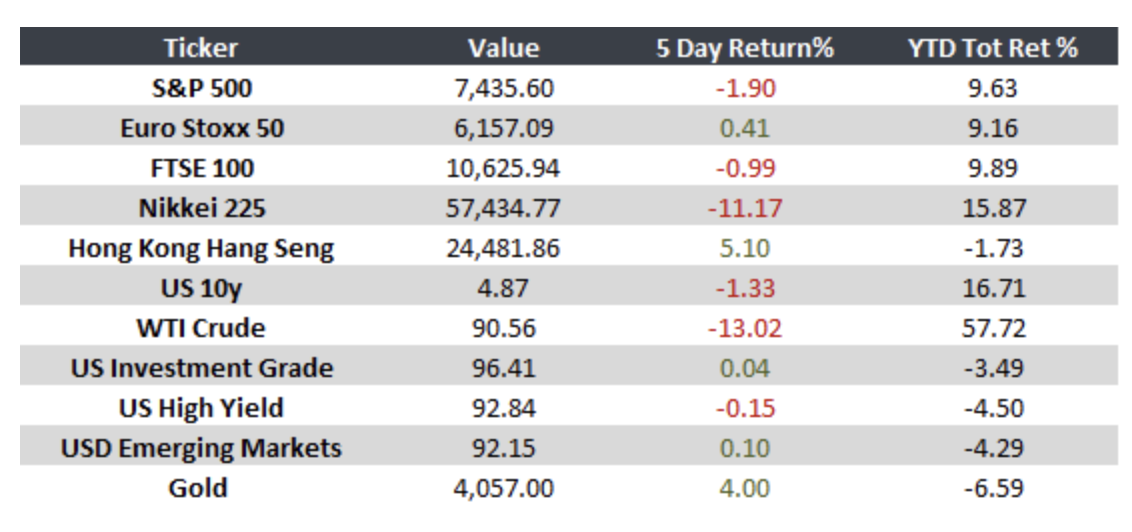
Democrats took control of Congress and the Nasdaq posted its largest drop since April 2025. Meanwhile, inflation accelerated in Europe and the Bank of England raised rates; in Mexico, Banxico surprised with a cut.
United States
- Democrats took control of Congress and the Nasdaq had its largest drop since April 2025 on semiconductors and AI. Nonfarm payrolls added 165,000 jobs, well above expectations.
Europe
- Eurozone inflation rose to 4.0% in October, its highest level since September 2023, driven by energy. The Bank of England raised its rate to 4.0%, its first increase since 2023.
Japan
- The manufacturing PMI fell in October, although employment maintained solid growth. Nominal wages rose 4.6%, their largest increase since 1997, supporting further rate hikes.
China
- The manufacturing PMI moderated in October but beat expectations and extended expansion to 11 months, supported by higher output and new orders.
Argentina
- Analysts cut their 2026 growth forecast to 0.7% and raised their year-end inflation expectation to 30.4%.
Brazil
- The Central Bank held its rate at 13.75% in November and paused cuts amid higher inflationary pressures, fiscal uncertainty, and weaker economic momentum.
Mexico
- Banxico surprised by cutting its rate 25 bps to 6.25%, even as inflation rose to 3.62%; the decision was 3-2. The manufacturing PMI fell in October, reflecting a contraction in the sector.
“Earn as much as you can, save as much as you can, invest as much as you can, give as much as you can.”
— John Wesley
Upcoming Events
- In the United States, the manufacturing PMI will be released on 11/10
- In the United States, the non-farm payrolls data will be released on 11/13
Monitor: