
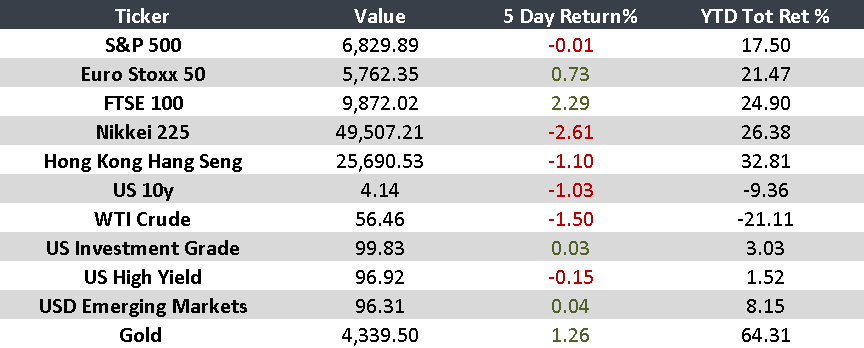
Week December 15–19
In a relatively calm week, employment and consumption indicators provided key signals across major economies. Central bank decisions continue to reflect a cautious, data – dependent approach, while global economies show divergences between production and consumption that reinforce the need for selective analysis heading into 2025.
United States
- Nonfarm payrolls exceeded expectations, adding 64,000 jobs in November.
- The unemployment rate rose to 4.6%.
- Headline inflation eased to 2.7% and core inflation to 2.6%.
Europe
- The ECB held rates at 2.15% and revised its growth outlook.
- Eurozone inflation stood at 2.1%.
- Germany and Spain recorded 2.6% and 3.2%, respectively.
- The United Kingdom cut its policy rate to 3.75%.
China
- Industrial production grew 4.8% year over year in November.
- Retail sales rose just 1.3%, the weakest increase since December 2022.
- Sharp declines in automobiles, household appliances, and construction materials.
Argentina
- GDP expanded 3.3% year over year in 3Q, below expectations.
- Manufacturing output declined 2.4%.
- The unemployment rate fell to 6.6%, approaching historical lows.
Brazil
- Economic activity declined 0.2% month over month.
- Agriculture helped prevent a deeper contraction.
- The central bank revised its GDP growth forecast upward and maintained a restrictive stance to contain inflation.
Mexico
- Banxico cut its policy rate to 7%.
- Retail sales increased 3.4% year over year, driven by strong online sales.
- Employment in the sector rose 1%, while wages increased 3.3%.
“The first rule of compounding: Never interrupt it unnecessarily.” — Charlie Munger
Key Upcoming Events
- United States: Quarterly GDP growth release — December 23
- United States: Labor market data release — December 24
Monitor
Returns as of 10 AM EST
