
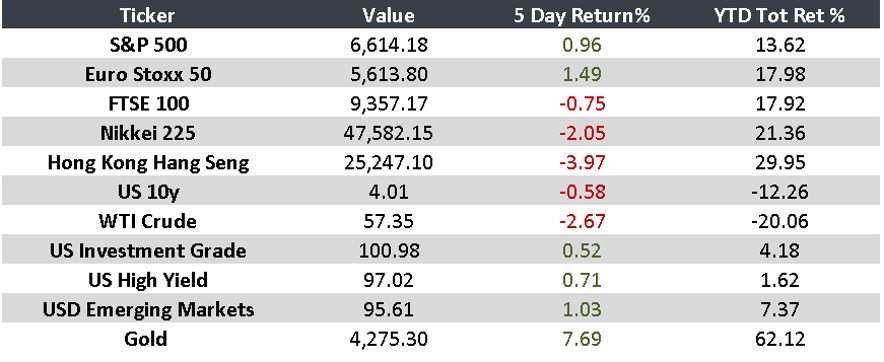
Week: October 13–17
Markets showed a mix of recovery signs and new challenges, driven by trade tensions, monetary policy decisions, and corporate earnings.
United States
- Tensions with China escalated following new statements from President Trump.
- Chair Powell suggested the end of the tightening cycle, opening the door to potential rate cuts.
- Banks reported solid earnings, though volatility persists among regional banks.
Europe
- German investor confidence rose less than expected.
- The U.K. economy grew 0.1% in August, but with downward revisions to prior data.
- The IMF urged the Bank of England to remain cautious, as inflation is expected to stay the highest in the G7.
Asia
- In China, exports rose 8.3% year-over-year in September, the fastest pace in six months.
- Inflation fell again (-0.3%), reflecting weak domestic demand and ongoing trade tensions.
- Producer prices dropped 2.3% annually.
Latin America
- In Brazil, the economy expanded 0.4% in August, below expectations. Analysts expect a deeper slowdown as monetary policy remains tight. The Central Bank maintained its benchmark rate at 15%.
- In Mexico, the IMF projects a fiscal deficit of 3.9% of GDP for 2025 — the highest since 2000. The government is assessing potential tariff adjustments for 2026, depending on U.S.–China trade developments.
“Risk comes from not knowing what you are doing.” — Warren Buffett
Key Upcoming Events:
- China: GDP, industrial production, and retail sales data — October 20
- United States: Consumer prices and new home sales — October 24
Monitor:
