
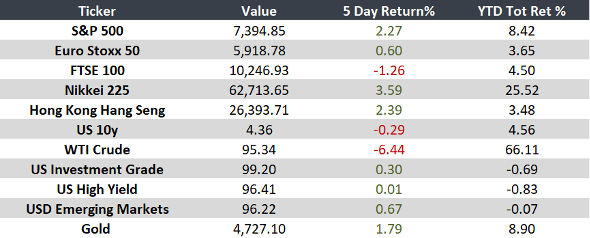
Week of May 4 to May 8
A week marked by inflation pressures and slowing activity
Recent data point to a moderate growth environment with persistent cost pressures. Inflation driven by energy and geopolitical tensions continues to shape monetary policy decisions globally.
United States
- Strong earnings (83% beating estimates) drive profit growth to ~23%.
- Employment exceeds expectations but is slowing.
- PMI signals rising cost pressures that could pass through to inflation.
Europe
- Industrial costs remain elevated and services PMI drops to a 62-month low.
- In Germany, weakness in manufacturing and services increases recession risks.
Japan
- Services activity slows, while central bank minutes suggest potential rate hikes.
- Energy shocks are raising inflation risks and pressure on exports.
China
- Composite PMI improves on stronger demand, but input costs reach their highest levels since 2022, pressuring margins and growth sustainability.
Argentina
- Industrial activity rises 5.0% year-over-year, driven by chemicals. However, sectors such as machinery and textiles remain in contraction.
Brazil
- Industrial production rebounds 4.3%, reflecting the positive impact of rate cuts despite a more challenging global environment.
Mexico
- Banxico cuts rates to 6.50% and inflation slows.
- Investment falls 4.2%, signaling weaker momentum and pressure on future growth.
“Time is your friend, impulse is your enemy.” — John Bogle
KEY UPCOMING EVENTS
- In the United States, Inflation data will be released — 05/12
- In the United States, PPI data will be released — 05/13
Monitor:
Note: Returns as of 10 AM ET.
