
Week of August 24–28
Resilient growth, persistent inflation and central banks under pressure.
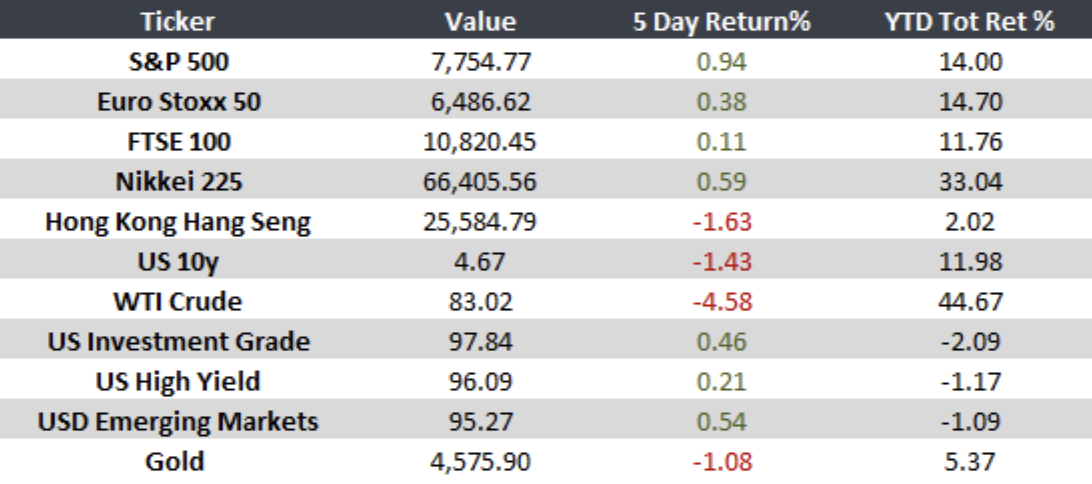
Markets closed out a week of mixed signals. Economic activity remained resilient across several economies, while inflation and interest rates continue to shape central bank decisions.
United States
- Nvidia stood out on strong AI demand, while GDP grew at a 1.5% annualized rate. PCE inflation reached 3.7%, keeping the debate over further Fed rate hikes in focus.
Europe
- The ECB is considering raising its policy rate to 2.50% in September as inflation remains near 3%. Germany grew 0.3% in Q2, while inflation expectations increased in the U.K.
Japan
- Debt-servicing costs could rise 17% in 2027, while markets expect the BoJ to raise its policy rate to 1.25% in September amid inflationary pressures and yen weakness.
China
- The government announced new financing and liquidity measures amid weak domestic demand, while industrial profits slowed and trade uncertainty remained elevated.
Argentina
- Argentina and Chile revived their cross-border mining treaty, seeking to unlock more than USD 20.7 billion in copper investment and reduce costs through shared infrastructure
Brasil
- Unemployment fell to 5.3% in the three months through July, its lowest level since December 2025. Employment reached a record high, while real incomes remained stable.
México
- GDP grew 1.4% quarter over quarter in Q2, while economic activity rose 2.8% year over year in June. Inflation reached 3.26% in the first half of August, with core inflation at 3.93%.
“All intelligent investing is value investing. Acquiring more than you are paying for. You must value the business in order to value the stock.” — Charlie Munger
UPCOMING EVENTS
- In the United States, PMI manufacturing data will be released 09/01
- In the United States, nonfarm payrolls will be released on 09/04
Monitor:

Quote: Indicative prices as of 10:00 AM EST
