Week of September 21–25
Higher rates and mixed activity signals keep central banks and global growth in focus.
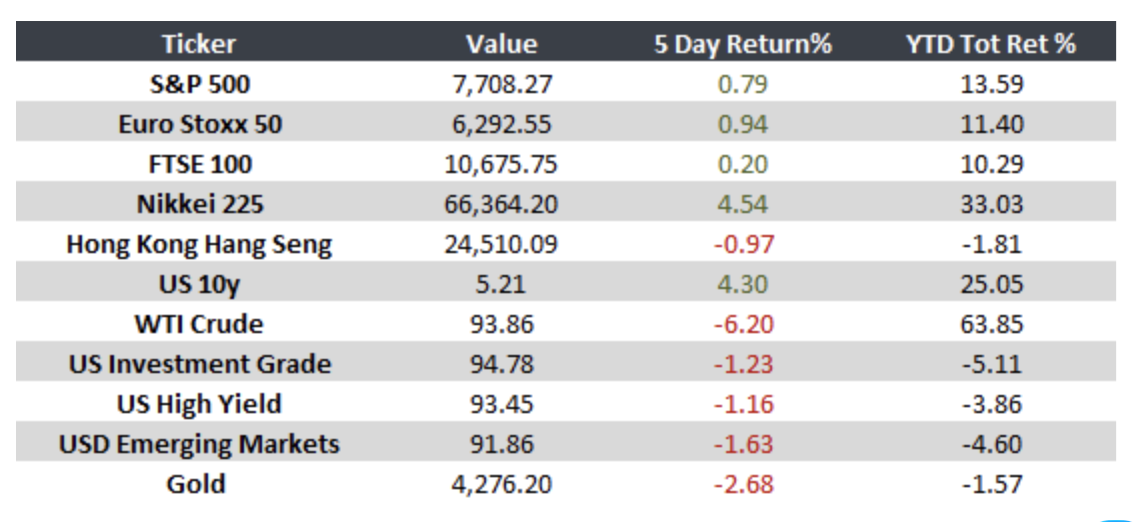
Markets experienced increased volatility as bond yields moved higher. While central banks assess their next steps, global economic activity continues to send mixed signals.
United States
- Treasury yields reached multi-decade highs amid expectations for higher rates. The labor market remained solid, while new home sales rebounded.
Europe
- Manufacturing sent mixed signals: the Eurozone remained stable, while the U.K. improved. High energy prices keep attention focused on the BoE’s next policy decisions.
Japan
- Manufacturing and services PMIs lost momentum in September. Activity continued to expand, albeit at a slower pace, while yen weakness kept cost pressures elevated.
China
- The People’s Bank of China announced daily liquidity injections of up to RMB 1 trillion to support the banking system ahead of the Golden Week holiday.
Argentina
- Economic activity contracted 1.4% year over year in July, reversing June’s growth and falling short of market expectations.
Brazil
- Consumer confidence fell in September to its lowest level since November 2022 as expectations deteriorated, although sentiment regarding current conditions improved slightly.
Mexico
- Banxico held its policy rate at 6.50%, while inflation rose to 3.42%. The OECD raised its 2026 growth forecast to 1.5%, although fiscal challenges remain.
“It’s not how much money you make, but how much money you keep, how hard it works for you, and how many generations you keep it for.”
— Robert Kiyosaki
Eventos importantes
- In the United States, Manufacturing PMI will be released 10/01
- In the United States, Nonfarm Payrolls will be released 10/02
Monitor: